Cash can look deceptively simple on a portfolio statement. For one client, it may be the down payment on a second home in six months. For another, it may need to cover a significant tax bill next quarter. A third may be holding more cash because markets feel uncertain.
Each client is holding cash, but each needs something different from it.
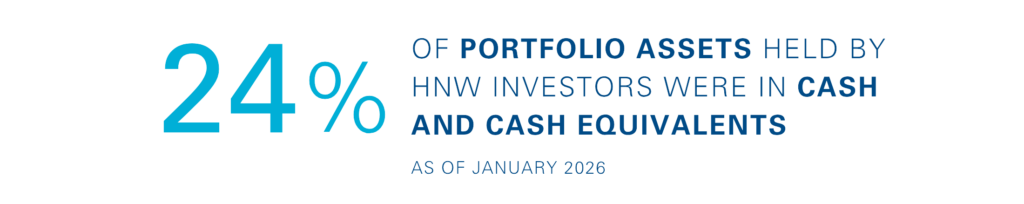
That distinction matters for high-net-worth (HNW) clients because liquidity rarely exists in isolation. A need for cash can quickly become a conversation about taxes, investments, lending, a business, or a private market commitment. Capgemini’s World Wealth Report found that HNW investors held 24% of their portfolios in cash and cash equivalents (as of January 2026).
For advisors, the opportunity is to look beyond the balance and ask a more useful question: What does this cash need to accomplish?
Start with the purpose, not the rate
HNW clients often have several demands on their liquidity at the same time. Some are predictable. Others are not.
The client buying the second home knows when the money will be needed. A business owner may need quick access to cash when a new business need or opportunity emerges. Another client may have a private investment commitment that requires funding on someone else’s timetable.
Those differences should shape the conversation. One practical approach is to organize liquidity around four needs:
- Immediate needs: Keep the cash available when needed and focus on preserving principal.
- Known future needs: Choose an option that keeps the money available when the client expects to need it.
- Flexible reserves: Keep enough flexibility for unexpected expenses while considering risk and potential return.
- Longer-term excess cash: Review whether money that is not needed soon could be put to better use elsewhere in the portfolio.
For HNW clients, this review becomes even more important when assets are spread across institutions. Capgemini found that 88% of HNW investors work with multiple wealth management firms, often to gain access to investments they cannot get through one provider. A client’s portfolio statement may therefore tell only part of the liquidity story.
Look beyond the headline yield
A higher yield does not necessarily mean a better liquidity solution.
Advisors also need to consider access, principal risk, maturity, deposit insurance eligibility, reinvestment risk, and how quickly the client may need the funds. Depending on the situation, the discussion might include insured cash, certificates of deposit, money market funds, short-term Treasuries, or other short-duration investments.
The tradeoffs matter. A client may be willing to give up some access for a known future expense but value flexibility more highly for an emergency reserve. The appropriate mix can also change as rates, spending plans, and the client’s circumstances evolve.
The objective is not to predict the next interest-rate move. It is to give each portion of the client’s liquidity a clear job.
Consider alternatives to selling investments
Sometimes the question is not where to hold cash. It is how to raise it.
Imagine a client facing a large tax payment while also holding investments they would prefer not to sell immediately. A sale may create tax consequences or interrupt a longer-term investment plan. In that situation, the advisor can compare available cash, portfolio sales, and borrowing rather than treating liquidation as the only option.
A securities-backed line of credit may allow qualified clients to borrow against eligible non-retirement assets while those investments remain in the portfolio. Borrowing also introduces costs and risks, including variable interest expense and potential collateral requirements. Advisors should evaluate those considerations alongside other funding alternatives.
For HNW clients, that broader view is important. Liquidity planning can connect investment decisions, tax considerations, borrowing needs, and upcoming obligations around the same client objective.
Make liquidity part of the client conversation
Liquidity needs rarely stay fixed. A business transaction, home purchase, tax obligation, family event, or new investment can quickly change what the client needs from their cash.
A simple place to start during the next portfolio review is to ask: What major uses of cash do you anticipate over the next 12, 24, and 36 months?
The answer can help identify cash with a clear purpose, cash that may need a different vehicle, and cash that may no longer need to sit on the sidelines.
Thoughtful cash management is ultimately about giving HNW clients flexibility as their financial lives become more complex. By connecting liquidity with investments, lending, taxes, and planning, advisors can help clients make those decisions from a more complete financial picture.
The more complex a client’s financial life becomes, the more valuable it is to connect the pieces. AssetMark can help advisors bring cash and lending, tax management, investment solutions, and planning support into a more coordinated client conversation.